
Mark Furman: Your real competitor is not who you think it is
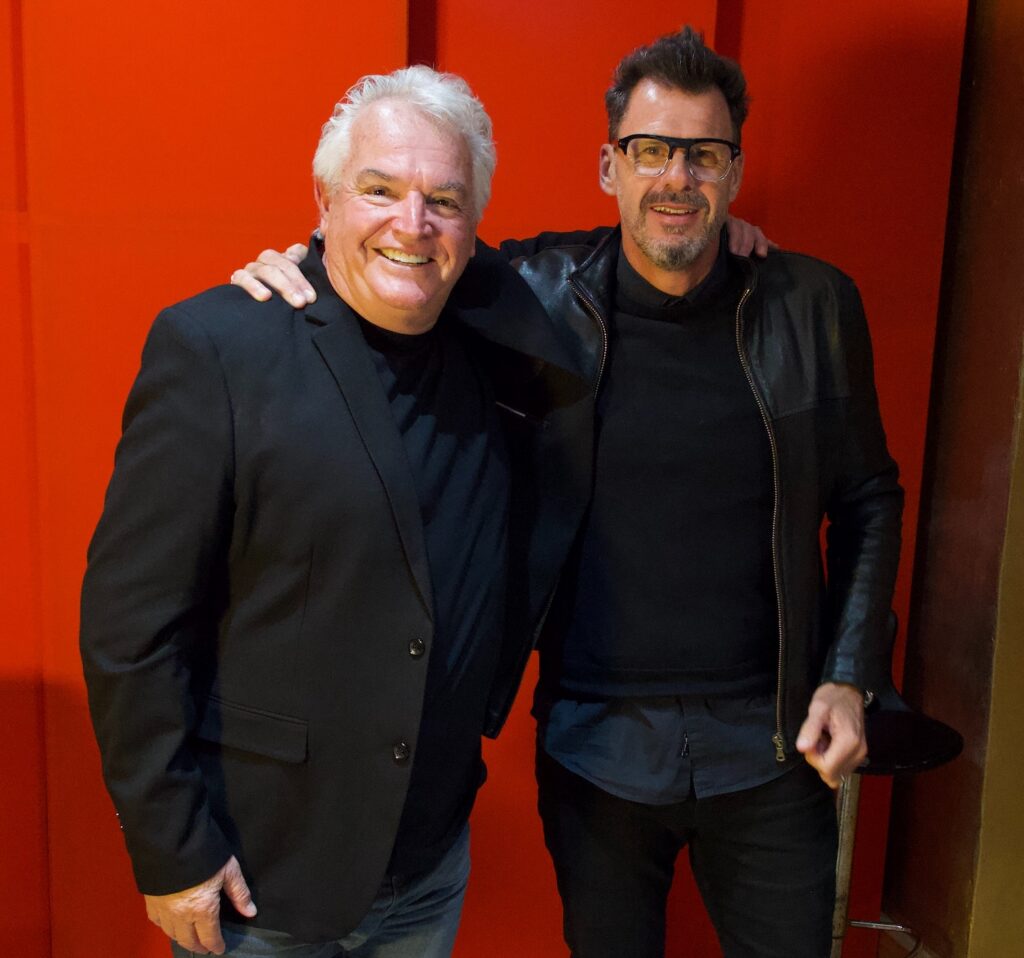
As an entrepreneur, strategist, speaker, and AI imagineer, Mark Furman has spent over a decade exploring the complexities of artificial intelligence. In this episode of the Business Unusual Podcast he sat down with Ralf Fletcher to cut through the media hype to explain why AI is not a threat to be feared but an incredible tool to help businesses and people in their everyday life. You’ll find out: Watch the full podcast on YouTube, or listen on Spotify and Apple Podcasts for conversations about doing good business in unusual times.
How much does cash cost?
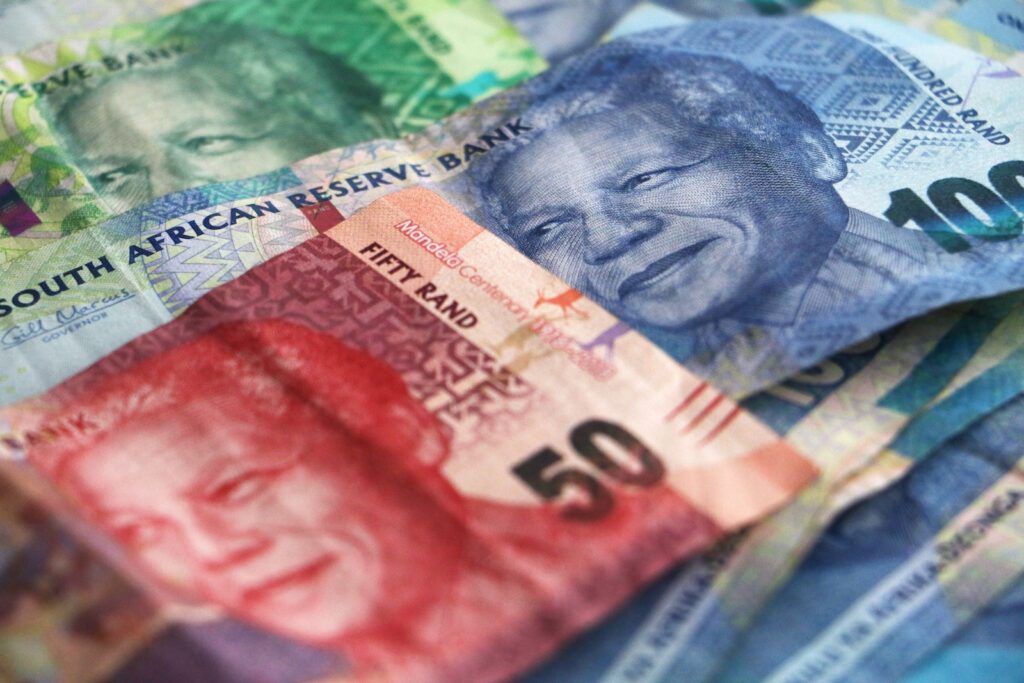
By Koketso Mamabolo Cash still rules everything around us. Across both the formal or informal economies, digital payments have yet to overtake cash as a significant component of South Africa’s payment ecosystem, despite the rise of fintech and payments services companies. More than half of all consumer transactions by volume are made in cash. As the South African Reserve Bank says: “The continued importance of cash is reflected in the extensive infrastructure required to manufacture, distribute, store, transport, access and accept cash through the economy.” In an effort to gain insights that could help in optimising the management of the lifecycle of local currency, the Reserve Bank conducted a study to quantify the operational and social costs associated with cash. The last such study was done by Mastercard in 2016 which pinned the cost of cash to consumers at R23-billion, or 0.52% of GDP. A decade later The Cost of Cash Research Study puts that figure at R88.5-billion per annum which is 1.2% of GDP. Based on the latest available population figures, that equates to almost R 1 400 per person. The Reserve Bank went further and deeper than previous studies. Using industry data, financial modelling, surveys, financial analysis, and benchmarking, the researchers identified the drivers of costs and the implications of using cash. Breaking down the costs The Reserve Bank breaks the cash ecosystem down into three tiers: essential industry services, essential banking services, and businesses (e.g. retailers and informal traders). The ecosystem begins with the first tier, the movement and storage of bulk cash between the Reserve Bank and cash centres, including the infrastructure. The commercial banks are in the second tier with the responsibility of distribution and providing access to cash through ATMs and bank branches. As of 2024, the ‘big five’ banks accounted for 90% of market share servicing almost 60 million retail banking customers. Tier 3 is the business, including retailers, taxi operators, and informal traders such as street vendors, and spaza shops. A report by Standard Bank estimates that eighty percent of businesses are outside of formal regulatory frameworks and that the market size of the informal economy could be close to R1-trillion. It accounts for around 40% of employment and its contribution to the economy could be as high as 11%. The R88.5-billion figure is a combination of both direct and indirect costs of cash. The direct costs are R43.5-billion per annum (49%) and consist of withdrawal fees, deposit fees, and the cost of travelling to access cash. The indirect costs make up a bigger proportion of the total (51%) coming in at R44.9-billion. These costs include travel time, crime-related costs, forgone interest, and “other economic inefficiencies”. The biggest direct cost is cash withdrawal fees (R17.7-billion). Queuing and transaction times indirectly cost consumers R19.5-billion per annum. Towards economic inclusion “The analysis indicates that costs incurred across Tiers 1 to 3, including embedded margins, are ultimately borne by consumers through a combination of explicit charges, pricing structures and broader economic incidence.” While higher income households are more likely to have shifted costs by using digital payments (which also come with fees), the cost of cash to lower income households is five times more as a share of income. On the other hand, informal traders run cash-heavy businesses and bear a higher cost of cash compared to formal retailers who have economies of scale. Just 10% of taxi drivers and 39% of informal traders accept electronic payments. With 64% of survey respondents indicating a preference for cash over digital payments, and the sheer size of the informal economy, reducing the cost of cash could have welfare benefits and improve financial inclusion. The stumbling blocks include a lack of access to technology, low trust in digital payments, a lack of digital literacy. Some of the policy recommendations include expanding cash-back at retailers, which only costs 12 cents per R100, compared to ATM withdrawals which cost 68 cents, and bank branches which charge R1.53 for every R100. “International experience demonstrates that reducing the cost of cash does not necessarily require eliminating cash. Several countries have successfully expanded digital payments while simultaneously preserving resilient cash ecosystems.” “Taken together, these case studies show that there is no single pathway to reducing the cost of cash. Rather, successful strategies typically combine digital innovation, efficient cash-management practices, supportive public policy and a continued commitment to financial inclusion and operation resilience.” Source: South African Reserve Bank
South Africa’s leading HR organisations crowned at the 2026 Future of HR Awards
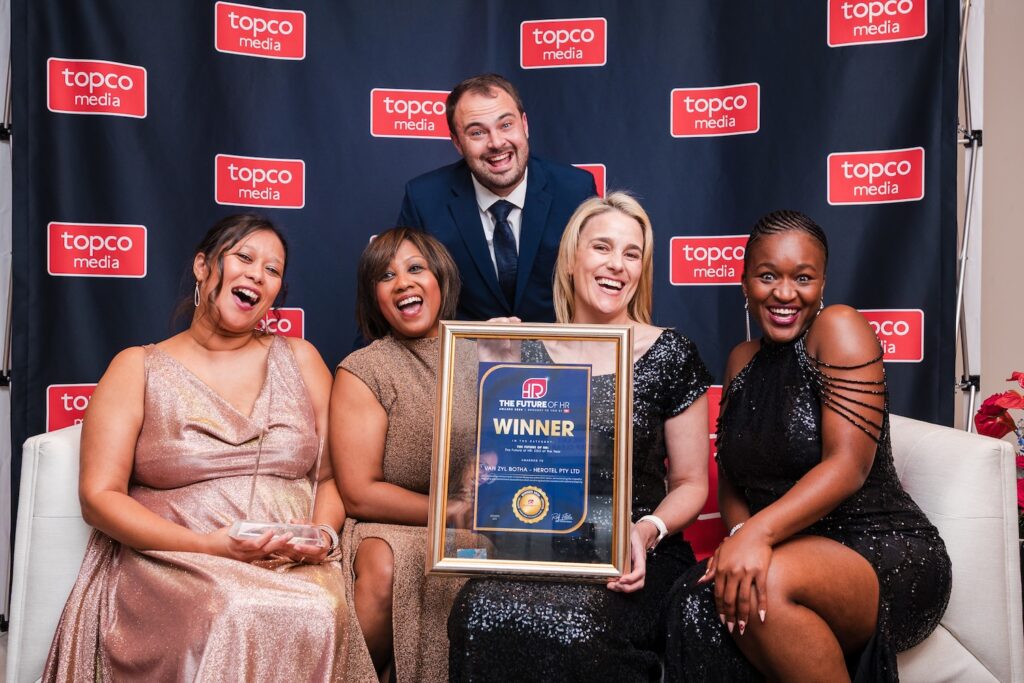
The Future of HR Awards 2026, brought to you by Topco Media, has announced its winners, highly commended recipients and finalists.
South Africa’s first smart town
At the height of South Africa’s electricity crisis, load shedding was particularly disruptive for a destination whose businesses depend heavily on visitors, restaurants, accommodation establishments and other tourism-related activities.
Five minutes a day could keep the physio away
As a physiotherapist working with corporate teams for more than 15 years, I’ve seen first-hand how small, consistent habits create meaningful change.
Future of HR 2026 puts people at the centre of national progress
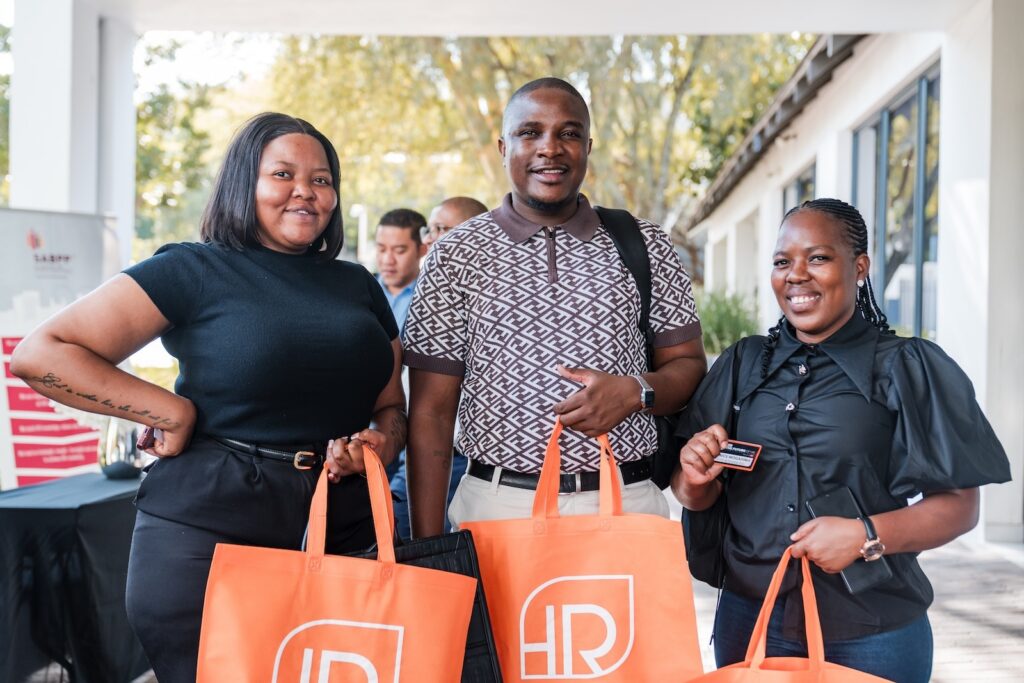
Moderated by broadcaster Clement Manyathela, the conference explored HR’s role in organisational and national progress.
The sales teams winning with AI aren’t using more of it. They’re using it differently.
Don’t commission an expensive, business-wide “get our data AI-ready” exercise before you’ve even proven the concept on one real problem.
Measure yourself against the rest of the pack: Why entering awards is good business
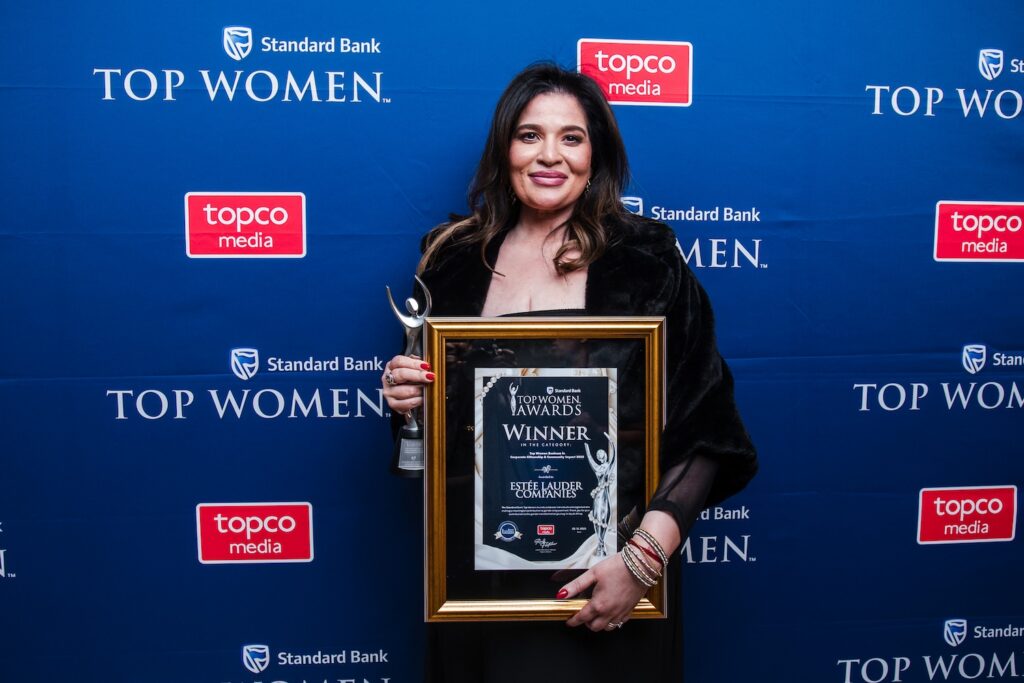
We see the celebrations, hear the acceptance speech and debate who we think should’ve won. But why do people and organisations enter awards?
Why mining needs a unified systems approach to sustainable transformation
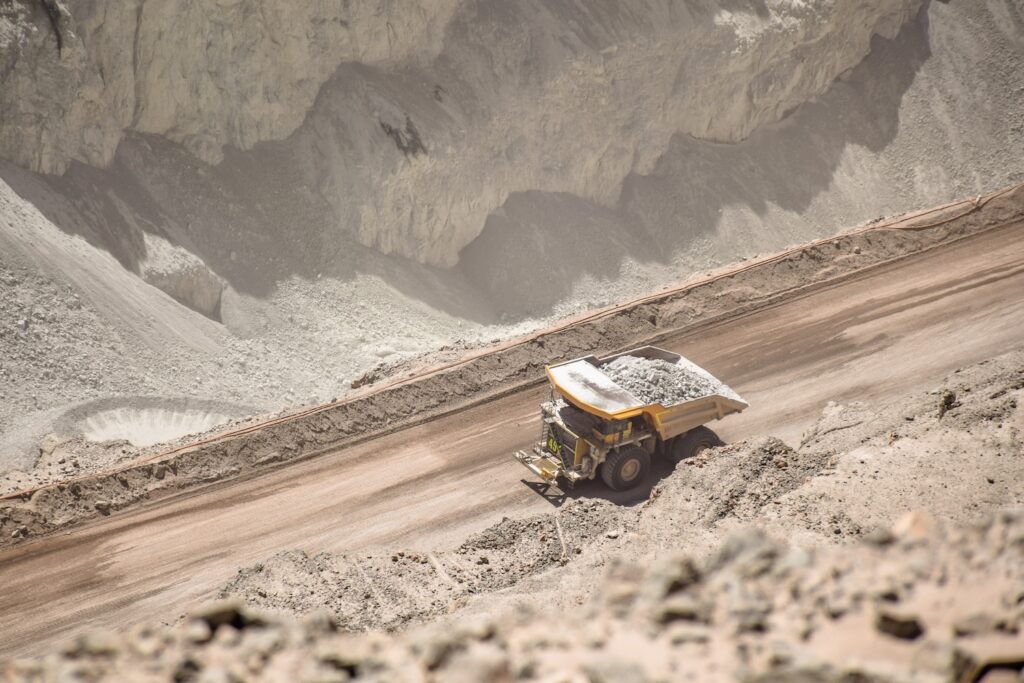
“As we at Wits Geosciences often say, there has never been a more critical moment to empower our communities.”
What’s the difference between funeral cover and life cover?
“Depending on a family’s circumstances, having one or both may make sense.”